
Coverage line
Nail salon property insurance: protecting what you own and the income it earns
Property insurance answers for the equipment, stock and build-out inside your leased unit, and commonly for the income lost while a covered loss keeps you closed.
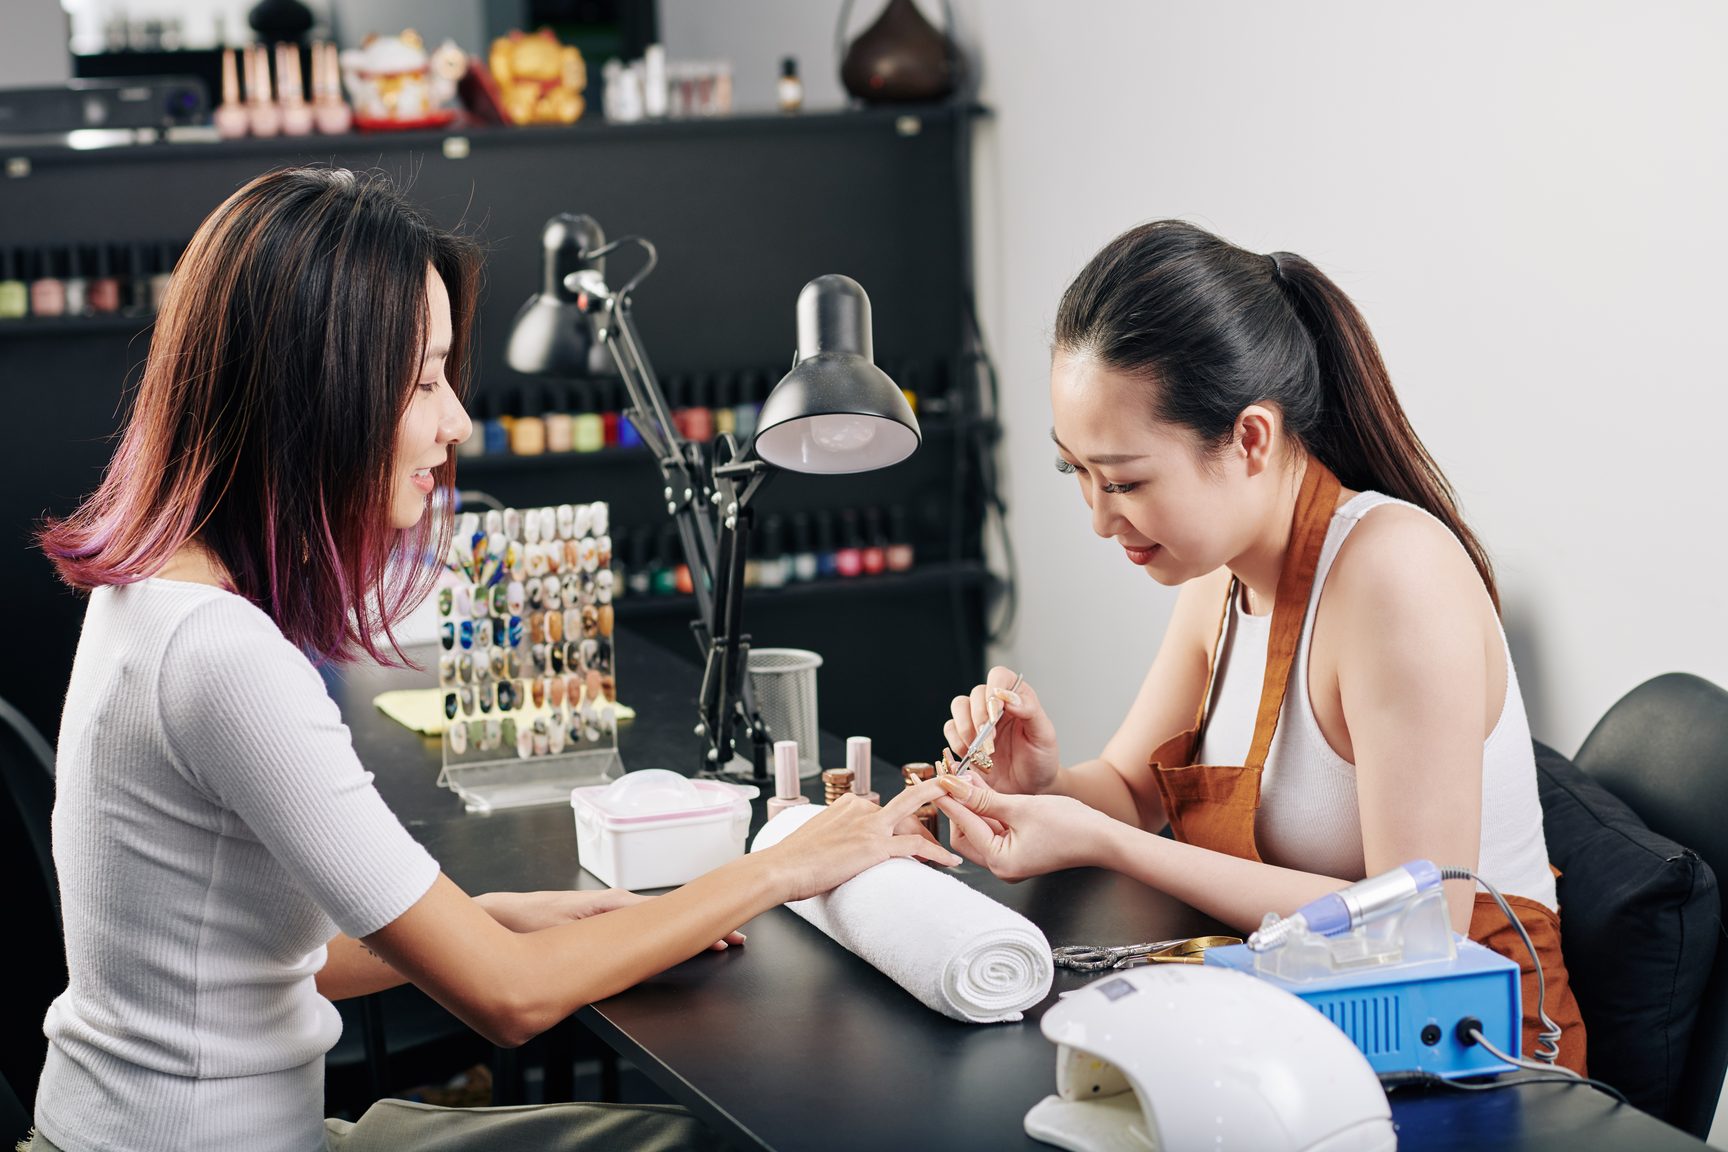
Nail salon property insurance pays to repair or replace the things the salon owns when a covered event damages them, and it commonly extends to the income lost while the doors are shut. It is the policy for your chairs, lamps, sterilizers, furniture, computer, stock and the build-out you paid for, not for the people who walk in.
A nail salon is an unusual pile of property to insure. Plumbed furniture, heat-producing lamps, sterilizing machines and shelves of solvents and monomers share a retail unit the salon may lease rather than own. The questions that matter are which of those things the policy names, who answers for the shell around them, and what you would do for income while the unit is repaired. Insurers file their own wording, so everything below describes how such policies are commonly written, and your own policy decides any real claim.
What nail salon property insurance generally covers and leaves out
The U.S. Small Business Administration describes commercial property insurance as protection against loss of and damage to company property from a wide variety of events. For a nail salon, the working list looks like this.
- Business personal property: pedicure chairs, manicure tables, curing lamps, sterilizing equipment, drills, furniture, the front desk and its computer.
- Stock and supplies: polish, acrylic powder and liquid, gel, and the retail inventory you sell.
- Tenant improvements and betterments you paid for, depending on how the lease and the policy treat them.
- Business income and extra expense, commonly as an addition to or part of the property policy.
- Equipment breakdown, commonly through an endorsement rather than in the base form.
What the policy generally leaves out is just as important, and several items belong to other coverage pages.
- A customer hurt in your space, or a customer’s property damaged by your work: that is general liability.
- A staff member hurt in the same event: that is workers’ compensation.
- Vehicles used for the business: that is commercial auto.
- Liability claims that outrun the underlying limit: that is umbrella, which does not sit above property.
- Flood and earth movement, generally excluded or sold separately, and wear and tear, rust and gradual deterioration.
A stack from the lasting to the consumable. At the base sits the build-out the tenant paid for. Above it sit the large fixed and plumbed equipment pieces. Above those sit the portable tools, lamps and furniture. At the top sits the stock that is used and replaced. Business income and extra expense sit beside the stack, answering for the time the doors are closed after a covered loss. No figures are shown.
The equipment that makes the salon run
Much of what a salon owns is equipment specific to the trade. Plumbed pedicure stations, manicure tables with built-in ventilation, ultraviolet and LED curing lamps, drills and the sterilizing equipment that keeps tools safe between clients all have to be replaced to reopen. If the policy lists business personal property in general terms, those items usually fall inside it, but how the policy values them matters as much as whether it names them.
Ventilation and extraction units deserve a specific look. They are part of how a salon controls dust and vapors, and the FDA advises good ventilation when using nail products. They can also be bolted to the space, which raises the same question as the build-out: whether the policy treats them as your equipment or as part of the building. Walk the salon with a list before you sit down with us, and name anything unusual.
The front desk is easy to overlook. A computer, a card reader, a booking tablet and the customer records on them are property too, and the cost of replacing them and rebuilding records is part of getting back to work. Ask how the policy treats electronic data, because some forms handle it separately from the hardware.
Stock, supplies and how product is stored
Product stock is business personal property as well, and it runs wider than the retail shelf: backbar polish, powders and liquids, gels, removers, tools, disposables and the retail shelf at the desk. A policy may treat inventory held for sale and supplies used in the work in related but not identical ways, so confirm both are named.
The CDC’s National Institute for Occupational Safety and Health lists acetone among the common chemicals in nail products. This page makes no claim about what any insurer requires. It is fair to say that how products are stored, and how much sits near heat or equipment, is the kind of practice an underwriter may ask about, and a fire is the loss that this policy exists to answer. Tell us honestly how you store product so the application matches the salon.
Build-out in a space you lease
A salon in a leased unit may have paid for a build-out: plumbing run to the pedicure stations, lighting, cabinetry, a reception counter, finishes that suit the work. These are tenant improvements and betterments, and they can be the costliest thing you put into the unit. If a fire gutted the space, the landlord’s policy would not necessarily rebuild what you paid for.
The lease decides who insures the building itself, and it can also decide who must repair what after a loss. We assert nothing about your lease. Read the insurance and repair clauses, note whether they say the tenant insures improvements, and bring the lease to the conversation so the property policy and the paperwork agree. Also ask whether the policy treats improvements as part of your property or as part of the building, since the label affects what is paid and how it is valued.
Business income and extra expense
Replacing a damaged chair does not replace the earnings that stop while the salon is closed. Business income coverage, commonly added to a business property policy or built into it, is aimed at that gap. As it is usually written, it responds when a covered cause of loss forces you to suspend operations, and it is meant to help with the income that would have come in plus continuing expenses such as rent and payroll.
Two features shape how it works, and both are described in words in the policy. A waiting period is the stretch at the start of a shutdown before the coverage begins to respond. The period of restoration is the time the policy considers reasonable for repairs and a return to operation. Extra expense, which usually sits alongside, helps with added costs of keeping the business going, such as temporary space. The key condition is a covered loss at your own location, so the cause matters again here.
Ready.gov describes a written business continuity plan to manage a business disruption. A policy pays money, but a plan tells you what you will do first: which clients you will call, where equipment will come from, how staff will be reached.
Equipment breakdown versus wear and tear
Base property forms are written around outside events such as fire and water. The failure of a machine from within is a different problem. Equipment breakdown, commonly offered as an endorsement, is aimed at mechanical and electrical failure, for example a burned-out motor in a pedicure chair, a failed sterilizer, a lamp that shorts, or an air-handling unit that stops working.
Wear and tear is the opposite. Policies generally exclude the slow decline of a component with age, along with rust, corrosion and defects in the item itself. A chair that has worn out is a replacement cost, while a chair that failed because of a sudden electrical event may be a claim. Where the line falls depends on the wording and the facts, so ask what the breakdown endorsement names and whether it covers the salon’s specific equipment.
Fire, water, theft and what is usually left out
The causes of loss that property policies commonly write for are fire, the sudden escape of water from a failed fitting or drain line, theft, vandalism, and storm damage. For a salon with plumbed stations, water is the one to study. Policies can distinguish a sudden event from a slow, unnoticed leak, and the difference can decide a claim.
Flood and earth movement are generally excluded or sold separately. FEMA states that flood insurance is a separate policy that can cover a building, its contents, or both, which is why flood is a question to ask on its own rather than assume. If your unit is on a low floor or the building has a water history, ask about flood as a distinct question. Theft deserves its own questions as well: whether employee dishonesty is covered, whether stock is covered in transit, and whether tools kept off site are included.
A two-column comparison. The first column lists what property insurance generally answers for: the salon’s own equipment, stock, build-out and lost income. The second column lists what is handed to other lines: a customer hurt or a customer’s belongings damaged, a staff member hurt in the same event, and claims that outrun the liability policy. No figures are shown.
Where property stops and liability starts
The seam is simple to state. Property answers for the salon’s own things. General liability answers for other people and their property. If a pedicure chair leaks and ruins your floor, that is property. If the same leak soaks the unit below or hurts a client who slips, that is liability, along with a claim by the landlord for damage to the building if the lease makes you responsible.
The customer’s belongings are the awkward case. A coat, handbag or phone damaged by your operations is generally a liability matter, because it belongs to someone else. Items you take into your care for safekeeping can be treated differently on some policies, so ask how yours handles customers’ belongings and do not assume.
One event can touch several policies. A fire may destroy equipment, injure a technician and close the salon. The equipment and lost income go to property, and the staff injury goes to workers’ compensation. Umbrella needs care here: it is generally written over liability lines, not above property, so a large property loss is not made larger by one. See umbrella for how that structure is usually built.
Limits and structure, in words
Property limits are about structure more than size. The first decision is how loss is valued. Replacement cost pays to buy new equipment of like kind, while actual cash value subtracts depreciation, which for a chair or lamp that has seen years of use can leave a gap between the check and the price of the new item. Ask which basis applies to each part of the policy, since it can differ between equipment, stock and improvements.
The deductible is the amount you absorb before the policy pays, and the choice of a higher or lower deductible trades premium for out-of-pocket exposure. Coinsurance, described in words, is a condition in some forms that asks you to insure to a stated proportion of the property’s value. If you carry too little, the payment on a partial loss can be reduced. Keep the stated value current as the salon adds stations.
High-value items can be scheduled, meaning listed individually so they are not lost in a general limit. Business income limits are best described as a period of time rather than a dollar sum, since the right question is how long the salon could be closed. Describe your own closure realistically and size the limit to that.
How we quote nail salon property insurance
We are an independent agency, and we place property coverage for nail salons with the 23 markets we work with rather than a single insurer. We start with an inventory of your chairs, equipment, stock and improvements, read the lease clause together, and ask how you store product. We then compare how each market words the items that matter most to a salon: water, breakdown, business income and improvements.
A quote is not a promise of coverage, and policy wording differs between insurers. We will tell you which parts of the policy to read and what to confirm before you sign.
Why Protect My Nail Salon
We are an independent agency that writes for one kind of business, so a nail salon’s quote for this policy is read against other salon quotes rather than against a general small-business form. Before we recommend a policy we read its exclusions and endorsements against the services you offer and against the insurance section of your lease, and we tell you where the two do not match.
Property coverage is one part of the program our nail salon insurance page sets out, and every coverage on one page puts it beside the other four. The question to take next is in our guide to what is in a nail salon insurance policy, because the declarations, exclusions and endorsements decide what the state rules above mean for a claim; the rest of our guides for salon owners are on the blog. We place coverage in 48 states, and a licensed agent reads every request.
For a closer look, read our guide to home-based nail salon insurance, which explains why a homeowners policy leaves the business side uncovered. We also have a guide to mall kiosk nail salon insurance, which covers a station in a common area and the equipment left there overnight.
Keep reading
Other coverage for a nail salon
Read more
Property insurance questions from salon owners
Does property insurance pay for my pedicure chairs if a fitting fails and floods the floor?
The sudden failure of a fitting or drain line can be a covered cause of loss for the chairs and other equipment the salon owns, as the standard form is commonly written. Gradual leaking, rust and wear are generally treated differently, and the policy’s water wording varies by insurer. Damage to a neighboring unit or to the landlord’s building is a liability question instead. Read your own policy, and ask us to walk through it.
Who insures the build-out I paid for if I only lease the space?
The lease decides who insures the building itself, and the tenant improvements you paid for can be written as a separate item on the tenant’s policy. Read the lease clause on insurance and repairs before you buy, then bring it to us so the policy and the lease line up.
What happens to my income if the salon is closed after a fire?
Business income coverage is commonly added to a business property policy, or built into it. As it is usually written, it responds when a covered loss forces the salon to suspend operations, and it is tied to a waiting period before it starts and a period of restoration while the space is repaired. Extra expense helps with added costs of operating from somewhere else. The details are in the policy, so confirm them before you need them.
Is a broken curing lamp or sterilizer covered?
Mechanical or electrical failure of equipment is commonly offered as an endorsement called equipment breakdown, not as part of the base form. Ordinary wear and tear, rust and gradual deterioration are generally excluded. Ask whether the equipment that keeps the salon open is named in the breakdown wording.
Does property insurance cover flood or earthquake?
Flood and earth movement are generally excluded from a commercial property policy or sold separately. FEMA describes flood insurance as a separate policy that can cover a building, its contents, or both. If the unit is in a low spot or the building has a history of water problems, ask about separate flood cover.
If a customer’s coat or handbag is damaged in the salon, is that a property claim?
Usually not. A customer’s belongings damaged by the salon’s operations are generally a general liability matter, because property insurance answers for what the salon owns. Some situations, such as items held for safekeeping, can be treated differently, so ask how your policy handles customers’ belongings.
Protect the salon you built
Tell us what is in the unit and what the lease says, and we will show you how the policies we can reach treat it.